- High-Value Home Insurance
Traditional vs digital high-value home insurance
Digital home insurance lets you get a quote, buy cover, and manage your policy entirely online, while traditional broker-advised insurance is arranged and adjusted through an adviser instead, usually by phone. Both are regulated the same way by the FCA; the process differs, the protection doesn't.
At a glance
- Digital-first insurers let you quote, buy, and adjust cover online; brokers typically handle changes by phone.
- Both are equally regulated by the FCA, with the same Financial Ombudsman Service protection for complaints.
- Speed and transparency are the main advantages of digital-first cover, especially for high-value homes.
- Human support still matters: check whether a dedicated adviser is available if you need one.
Rivr is a high value home insurance provider designed specifically to fill this gap. No call queue: an instant online quote for high-value homes, with the same adviser on hand when you need one.
What are the differences between traditional and digital home insurance?
Broker-advised insurance puts a person between you and the insurer: someone who gathers your details, recommends cover, and handles renewals on your behalf. Digital-first insurance removes that layer. You enter your own details online and see the price and terms immediately, while the underwriting still happens behind the scenes.
| Broker-advised | Digital-first (Rivr) | |
|---|---|---|
| Getting a quote | A call or a form, then a wait for quotes to come back | Online in minutes, or a call with an adviser instead if you'd rather not do it online |
| Making changes | Typically another call | Through your online account, any time |
| Fees | Often includes admin, mid-term change, or cancellation charges | No admin, cancellation, or mid-term adjustment fees |
| Payment | Annual, or a broker-arranged instalment plan | Annual in full, or monthly through our premium finance partner, Bexhill |
| Making a claim | Reported to the broker, who liaises with the insurer | Reported online, handled by a dedicated specialist team and an adviser |
| Ongoing contact | A named contact from the start | The same adviser throughout, alongside online self-service |
The digital-first column above reflects Rivr specifically. Other digital-first insurers may not match every line of it.
What is digital home insurance?
Digital home insurance is buildings and contents cover that can be quoted, bought, and managed entirely online, without a broker or call centre handling each step. The underwriting still happens in the background; only the customer's side of the process changes. Rivr is one example: a UK broker built specifically around this model for high-value homes.
Does digital home insurance come with human support?
Digital-first doesn't rule out human contact. Most reputable digital insurers still provide a route to a person, usually a phone line or a named contact, for claims and for anything too complex to resolve through an online form.
What it does mean is that day-to-day account management (checking your policy, updating details, paying your premium) happens without needing to call anyone. The trade-off is real: digital-first insurance assumes you're comfortable handling quotes, renewals, and policy changes online, rather than talking them through with an adviser from the start.
Rivr pairs its online service with a dedicated adviser for claims and anything that needs a real conversation. There's no call centre queue to go through first, and a call with an adviser is available even at the quote stage, for anyone who'd rather not do it online at all.
Is digital home insurance regulated by the FCA?
Yes. Digital and traditional home insurance are regulated the same way, whether you buy through a broker, a comparison site, or directly online. Every FCA-authorised firm has to meet the Consumer Duty, a single fair-value standard applied to all of them.
The Financial Ombudsman Service is available to anyone with a complaint against a regulated firm. Rivr itself is authorised as an Appointed Representative of Innovative Risk Labs Ltd, regulated by the FCA like any other UK insurance intermediary.
How do I get an online quote for high-value home insurance?
For a high-value home, a digital-first quote usually means entering the rebuild cost, the contents value, and any specific risks (listed buildings, high security requirements, valuable collections) once. The price comes back in minutes; a broker would need to gather quotes from several insurers first.
That speed has a limit: unusual or very high-value properties sometimes still need a follow-up review before the quote is confirmed, since automated pricing can't price every complex risk instantly. With Rivr, that review happens after your online quote, when a human underwriter checks the details before your policy is confirmed.
How does digital home insurance work at Rivr?
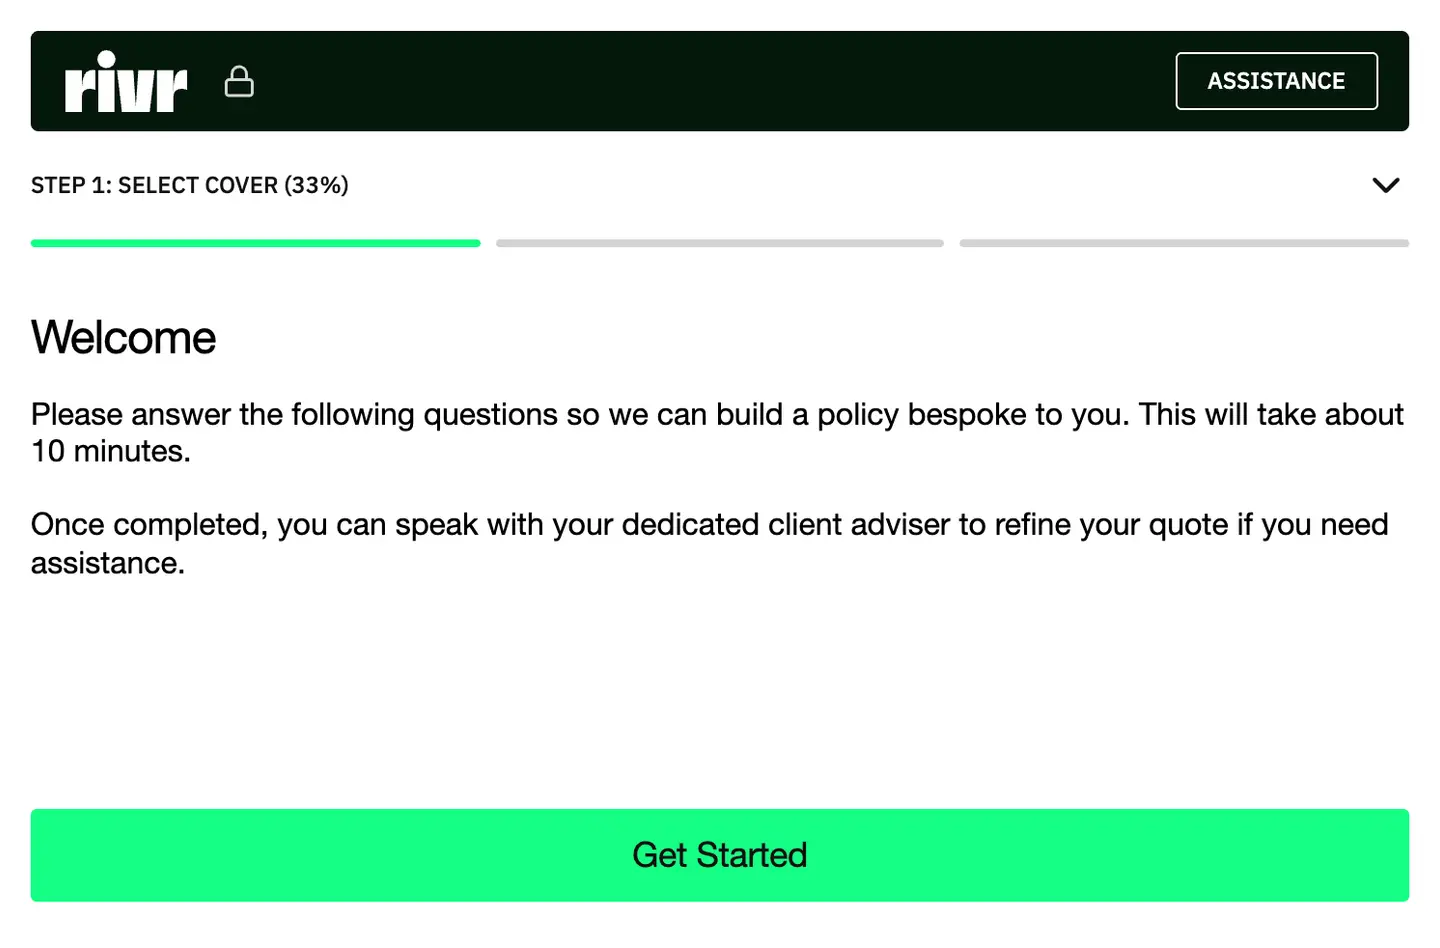
Rivr launched in 2024 on the premise that a fast digital quote and a named adviser don't have to be a choice. The process is straightforward:
- Enter your property details, rebuild cost, and contents value online, typically around five minutes.
- Get an instant, bespoke price.
- A human underwriter reviews the policy before it's confirmed, to check it actually fits the property.
- Buy and manage cover through your online account, any time.
- If you need to claim, it's managed online alongside the rest of your policy, with a dedicated specialist team and an adviser on hand.
Get high-value cover, the digital-first way
Rivr's high-value home insurance is quoted online in minutes, with a human underwriter checking the details before your policy is confirmed. Whether you need buildings cover, contents cover, or both together, it's managed the same digital-first way. Skip the call queue and the broker fees. Get your price, manage everything from your account, and know the same adviser is on hand whenever you need one.