- Buildings Insurance
Do You Need Building Insurance? 10 Reasons You Might
Wondering if you need building insurance? This guide explains when it’s required, what it covers, and 10 reasons it matters for homeowners.
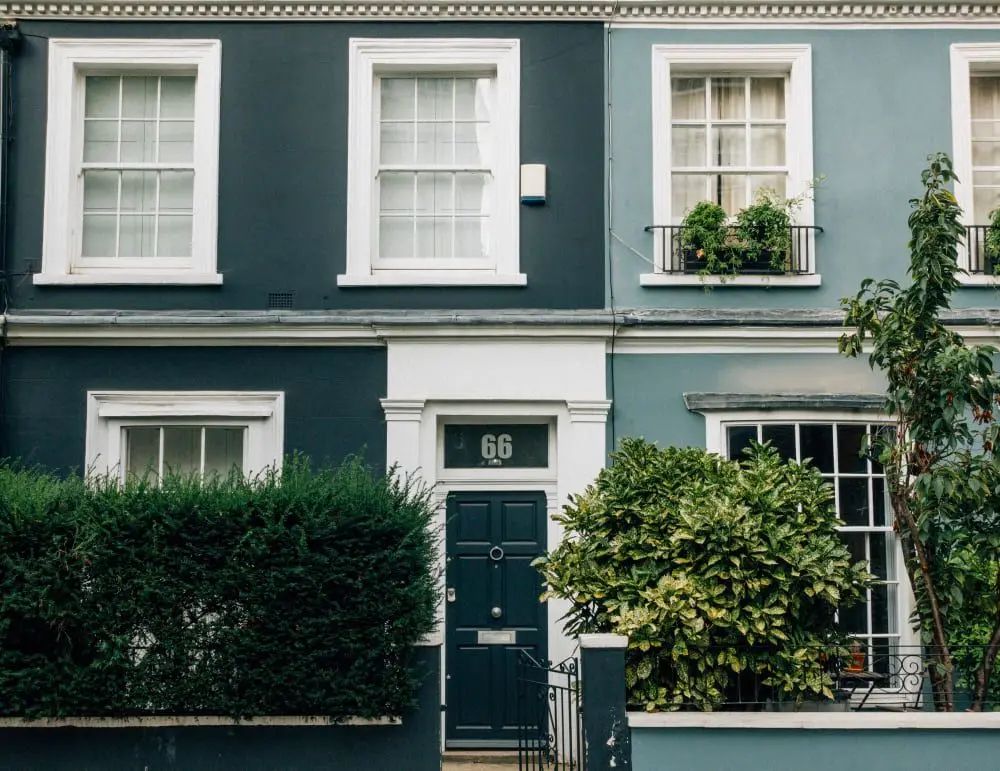
protect your listed home the right way
Our listed building insurance is tailored to homes of special architectural or historic interest. From Grade II properties to ones of exceptional significance, your cover reflects what makes it irreplaceable.
tailored protection for listed homes and heritage buildings
building insurance that values you
Rebuild or repair in the same form, style and condition as new. Up to 36 months’ alternative accommodation if uninhabitable after an insured event.
professional fees and compliance costs covered.
Architect and surveyor fees plus costs to meet Government or Local Authority requirements, within policy limits.
request a quote with ease
Digital-first cover, tailored advice, and your own advisor. Excess waived on claims over £25,000.
providing the cover you need
A listed building is one that is officially protected because of its special architectural or historic interest. These properties sit on a statutory list maintained by local authorities or Historic England.
There are three main grades of listed building in the UK, each reflecting a different level of significance and protection.
Owners must obtain listed building consent from their local planning authority before making repairs or alterations. The aim is to preserve the building’s architectural importance and overall historic interest.
Because of this, listed property insurance needs to cover full rebuild costs, including specialist materials, traditional labour, professional fees and permissions. Standard home insurance often does not provide this level of protection.
Our insurance offers tailored cover for Grade II and other listed homes, with specialist advice and support from experienced surveyors.
Explore our guide to listed building restoration to better understand consent, planning and repairs for your listed home.
Read our restoration guideListed homes have unique protection needs because of their historical and architectural importance. Repairs and rebuilding usually require consent from your local council or conservation officer.
Work must preserve the building’s heritage, often using traditional materials and methods. This can significantly increase the cost and complexity of reinstating the property after damage.
Standard home insurance frequently excludes or limits cover for these specialist repairs, permissions and materials. Without adequate listed property insurance, you may face large and unexpected expenses after an insured event.
Our listed building insurance is designed to reflect the true cost of reinstating a protected property and meeting regulatory requirements.
Protecting a listed building is about combining the right insurance with practical steps that reflect how the property is used and maintained.
at a glance
We insure to the sum insured you choose, so your cover reflects the value of your home and contents.
Get an instant quoteyour cover
We cover the physical structure of your home, any outbuildings, decorative finishes or permanent fittings in your home.
If you are carrying out building works on your home, we will cover you up to £100,000, but let us know if it's going to cost more than this.
Where a current Rivr-authorised survey is held, the insurer pays the full rebuild cost even if above the sum insured. Grade 1 listed buildings are excluded.
If you can't live in your home for up to 3 years due to some insured damage, the insurer will pay for somewhere else for you to live.
The insurer will pay for damage due to forced entry during a medical emergency or to prevent damage to your home.
The insurer will pay for any damage caused accidentally.
Policy documents
Only a summary of the policy’s coverage is presented on this page. Read these documents to fully understand what is and isn’t covered.
what we offer
Get started online in minutes. No paperwork.
High Value buildings, contents and valuables in one policy.
Specialist cover for your contents and valuables.
Standalone buildings cover designed for high value homes.
your dedicated client adviser
Get an instant quote and manage your policy online, whenever it suits you. When you would rather talk, your dedicated client adviser is there to help you refine your quote, answer questions during your policy and support you through a claim.
client reviews
faq
Insurance can be complicated. Here are answers to the questions we are asked most.
The policy is insured by two of the largest insurance companies in the world, which are both A- rated for their financial strength. The Buildings, Contents and Liability cover is insured by Accelerant Insurance UK Limited. The Property Emergency and Family Legal Solutions are insured by ARAG Legal Expenses Insurance Company Limited.
We can insure Grade II*, and Grade II listed homes in England and Wales, and Category B and C listed properties in Scotland, subject to individual underwriting.
Yes. Rivr can insure many non-standard homes, including timber, wattle and daub, subject to individual underwriting and approval.
If you hold an up-to-date, Rivr-authorised survey, the insurer pays the full cost to rebuild or repair at the time of loss, even if it exceeds the buildings sum insured.
We cannot offer cover for Grade 1 listed buildings.
Yes. After a valid claim, our policy includes cover for debris removal, architect and surveyor fees, and costs required to meet Government or Local Authority regulations, up to 25% of your buildings sum insured.
Yes. Unlike many insurers, we continue to cover your home while renovation works are taking place, provided the contract value for the works is under £100,000.
If your renovation costs exceed this amount, we can look to arrange specialist renovation cover through one of our trusted insurance partners.
Consent is required for any demolition, including partial, and for any internal or external alteration or extension that affects the building’s special architectural or historic interest. It can also apply to structures within the curtilage that predate 1 July 1948. Like for like repairs that do not affect character may not need consent, but confirm with your Local Planning Authority.
Consent is separate from planning permission, unauthorised works are a criminal offence, and there is no application fee in England.
Prices vary by rebuild cost, construction, location, and claims history. In many cases it is higher than a standard home because repairs may need approved traditional materials and specialist trades.
Standard buildings insurance is designed for typical homes, while high-value buildings insurance is tailored for properties with a higher rebuild cost, specialist materials, or unique architectural features. It provides broader protection, has higher limits, and more extensive coverage for luxury finishes and bespoke elements that standard policies may not fully insure.
journal
Wondering if you need building insurance? This guide explains when it’s required, what it covers, and 10 reasons it matters for homeowners.
Use this step-by-step guide to understand what buildings insurance covers, how claims work, key exclusions, and how to choose the right rebuild cost and optional extras.
In this guide, we’ll explore what buildings accidental damage cover includes, who it benefits, and whether it’s worth having in 2026.
3 simple steps