- Buildings Insurance
Unoccupied Commercial Property Insurance: Cover, Costs and Conditions
Vacant shops, offices or warehouses that are left unoccupied for any length of time face significantly higher risks than buildings in regular use. Vandalism, theft, water damage and unnoticed maintenance issues can escalate quickly, while liability claims from trespassers or contractors can expose owners to serious financial loss.
Without the right insurance in place, even a short unoccupied period can leave your investment exposed to costs you can't easily recover. That is why securing the right cover as soon as a commercial property is left unoccupied is essential.
At a glance
- Standard cover often restricts or removes protection once a commercial property has been empty for more than 30 consecutive days.
- Core buildings cover typically includes fire, storm, flood, malicious damage, attempted theft, and property owners' liability.
- Insurers expect active risk management including inspections, drained pipes, working alarms, and tidy grounds.
- Choosing the right policy term and accurate rebuild costs helps avoid overpaying or underinsuring.
Get a quote
rivr specialises in high-value home insurance for residential properties: buildings, contents, and valuables under one digital-first policy. Commercial property sits outside that. rivr doesn't provide unoccupied commercial property insurance directly, but our partner PolicyPowerhouse specialises in exactly this, from single retail units to full warehouse portfolios.
What is unoccupied commercial property insurance?
Most standard landlords insurance policies only cover a property during short periods of unoccupancy, typically up to 30 days. After that, specific restrictions apply, and specialist cover is required to remain protected.
Unoccupied commercial property insurance is designed for commercial premises that are left empty beyond this grace period. It applies to situations such as:
- Empty retail units between tenants
- Offices awaiting sale or refurbishment
- Industrial units after a move-out
- Mixed-use premises with vacant ground-floor space
Insurers classify these as unoccupied properties, which carry higher risk profiles than occupied sites.
This type of insurance is often referred to as vacant property insurance, unoccupied property insurance, or unoccupied commercial property insurance. A standard commercial property policy is not suitable here, as it typically excludes key risks once a property has been empty for more than 30 days.
Residential versions of unoccupied cover also exist, useful for empty houses such as second homes, holiday homes, or those awaiting sale. These are typically referred to as unoccupied home insurance.
How is this different to unoccupied house insurance?
Although both types of insurance protect buildings that are temporarily empty, there are key differences between the two:
| Feature | Unoccupied Home Insurance | Unoccupied Commercial Property Insurance |
|---|---|---|
| Primary use | Residential homes | Shops, offices, warehouses, mixed-use units |
| Common risks | Theft, escape of water, vandalism, fire | Theft of plant, copper, malicious damage, public liability |
| Inspection frequency | Every 30 days | Every 7 to 14 days with logs and photos |
| Security requirements | Locks, alarms, drained systems | Shutters, security patrols, alarm logs, boarded access |
| Legal considerations | Planning consent may be required for changes | Must meet lease or freeholder conditions; business use must be disclosed |
Why does an empty commercial site need different treatment?
An empty or vacant site faces:
- Theft and attempted theft of copper pipes, wiring and plant
- Arson and malicious damage by intruders or squatters
- Burst pipes, roof leaks or mould that escalate because no one spots them
- Trip hazards that lead to claims under property owners' liability insurance or public liability
Standard policies are built around daily occupation: alarms set, water running, prompt reporting of issues. Once a building is empty, that assumption collapses. Most insurance companies either strip cover to “FLEA” (Fire, Lightning, Explosion, Aircraft) or apply tight conditions. This basic cover is often limited to catastrophic risks only and excludes theft, escape of water, and liability.
A dedicated unoccupied commercial property policy provides broader protection, subject to compliance with conditions.
Always speak to a broker or insurance provider to confirm the specific policy terms and compliance requirements.
What cover does unoccupied commercial property insurance provide?
Every insurer’s schedule differs, so check full details, but expect the following key features:
| Core cover | What it includes |
|---|---|
| Buildings insurance | The structure, fixed glass, fixtures, boundary walls and gates |
| Contents insurance | Any remaining stock, plant or goods left onsite |
| Property owners' liability / public liability | Covers injury to others on site. Serious incidents, including accidental death, can lead to large claims |
Optional or add-on protections
- Legal expenses/legal liability/legal costs to pursue or defend disputes (e.g. trespassers, contractors).
- Loss of rent (if you’ve got a sitting tenant in part of the building, or a lease due but delayed).
- Emergency repairs or call-out cover to keep the property secure (or office/warehouse secure).
- Additional cover for specific perils, high-value plant or art left in reception areas.
Common exclusions
- Gradual deterioration, wear and tear, or defects you already knew about
- Unexplained losses and mysterious disappearances
- Major structural works that weren’t disclosed
- Long-term escape of water if the system wasn’t drained or heating maintained
- Criminal acts by you or your agents
5 Tips for meeting insurer requirements and reducing risks
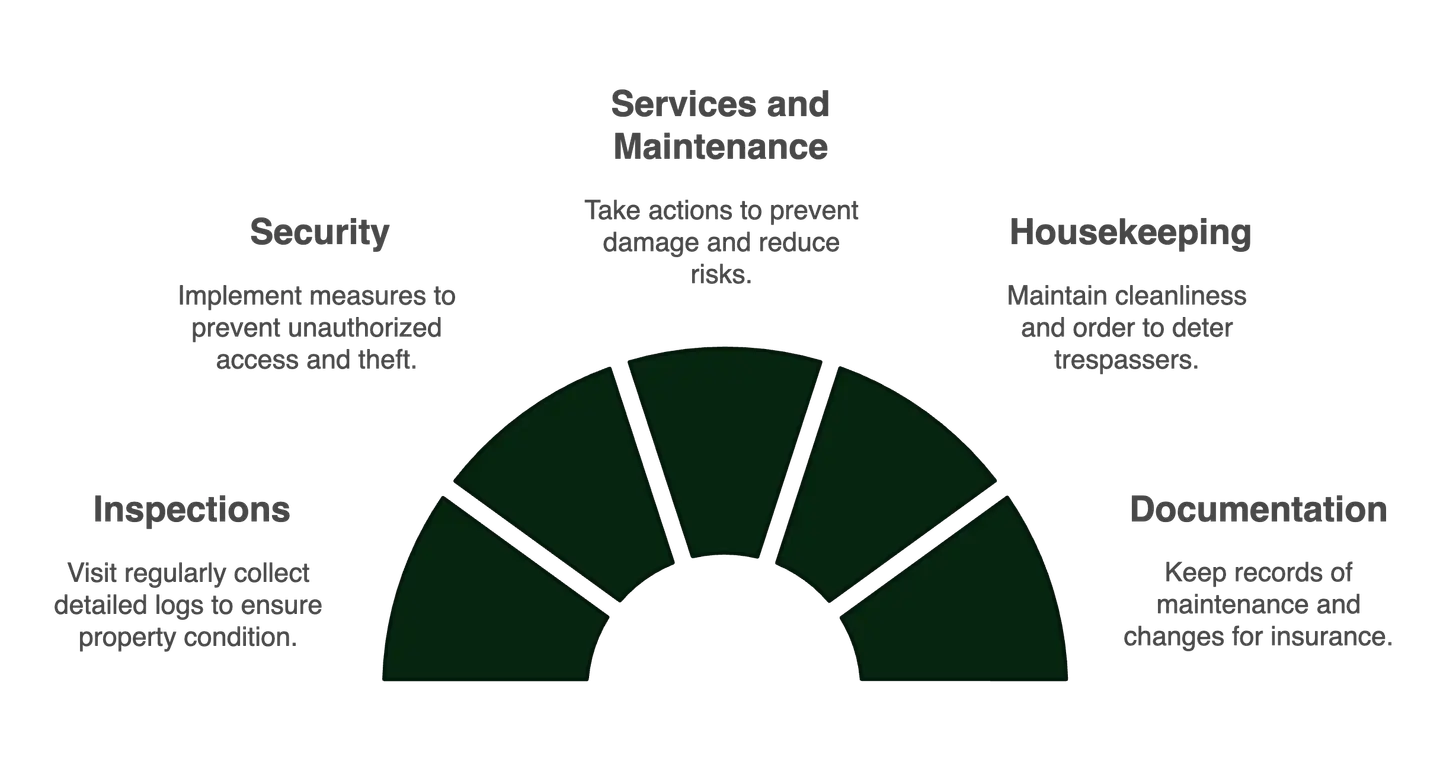
Some insurance providers reward owners who show they’ve thought ahead, offering improved terms or lower premiums. Typical conditions to keep unoccupied property insurance cover intact:
- Inspections Visit at least every 7 or 14 days (your wording will say).Log each visit, including date, time, condition found, and photos. Digital checklists are gold.
- Security Lock all doors and windows; fit good-quality padlocks and shutters.Activate any alarm system. If you don’t have one, consider a temporary monitored unit.Remove scrap metal, display units and attractive plant.
- Services and maintenance Turn off and drain water unless frost protection is required.Keep gutters clear and roofs checked after storms.Switch off non-essential electrics to cut fire risk.
- Housekeeping Clear rubbish and combustible waste quickly.Maintain lighting externally so trespassers aren’t tempted.
- Documentation Keep copies of invoices for boarding-up, alarm maintenance, or contractor work.Update your broker the moment the situation changes, like a new tenant, start of renovation, or partial occupation.
These actions both protect the building and make any claim smoother.
How do I get the best value from my insurance?
A few smart moves can trim costs and boost certainty:
Compare cover, not just price: Two policies may both say “accidental damage”, yet one excludes contractors.
Flexible periods: Ask for 3, 6, or 12 months. Short void? Go for a short period to avoid overpaying.
Accurate sums insured: Revisit rebuild costs so you don’t underinsure the shell and end up with a reduced payout.
Bundle portfolios: Landlords with multiple unoccupied properties might save by combining policies under one specialist unoccupied property insurance scheme.
Work with a broker: An experienced broker will already know which insurance providers are actively seeking this type of risk and which are more selective.
Leverage your other covers: You may still hold buildings insurance or contents insurance for parts of the estate; keep that context handy.
Checklist to prepare for an unoccupied property insurance quote
- Define the period you need to insure the vacant property (3, 6, 12 months?).
- Confirm the rebuild costs with a survey or indexation tool.
- List all security measures currently in place.
- Decide which additional cover you want (e.g. legal expenses, loss of rent).
- Gather your inspection plan: frequency, person responsible, photo evidence.
- Keep contact info handy for contractors to act fast on leaks or broken glazing.
- Have your old policy wording ready; brokers can see what you had and fill in the gaps.
Tailored cover for high value homes
rivr is a high-value, digital-first home insurance provider built around the needs of modern lifestyles. We provide tailored home and contents cover for primary residences, with a focus on clarity, speed, and simplicity.
If your property will be left unoccupied for an extended period due to probate, renovation, or travel, we can help you stay protected with the right level of cover.
For commercial properties, our partner PolicyPowerhouse offers specialist cover designed for unoccupied shops, offices, warehouses, and mixed-use buildings.